THE PROBLEM
The "Silent Risk"
You underwrote them thoroughly. They looked great. Then six months later their DOT rating tanks, a judgement pops up, or their registration lapses. By the time your annual review happens, the damage is done.
Most factors catch fraud at the door. ROX catches deteriorating clients before they damage your book.
Get Started Free
Credit risk monitoring software re-checks funded clients on the cadence you set, then alerts your team when something changes. ROX does this for factors, lenders, and MCA funders: you choose what to watch and how often, and ROX pulls the updates, compares them to the last pull, and flags what moved.
THE PROBLEM
You underwrote them thoroughly. They looked great. Then six months later their DOT rating tanks, a judgement pops up, or their registration lapses. By the time your annual review happens, the damage is done.
THE SOLUTION
Pick what to watch and how often. ROX automatically pulls updates and alerts you when something changes.
HOW IT WORKS
Watch a quick overview of how ROX monitoring works.
CLIENT MONITORING
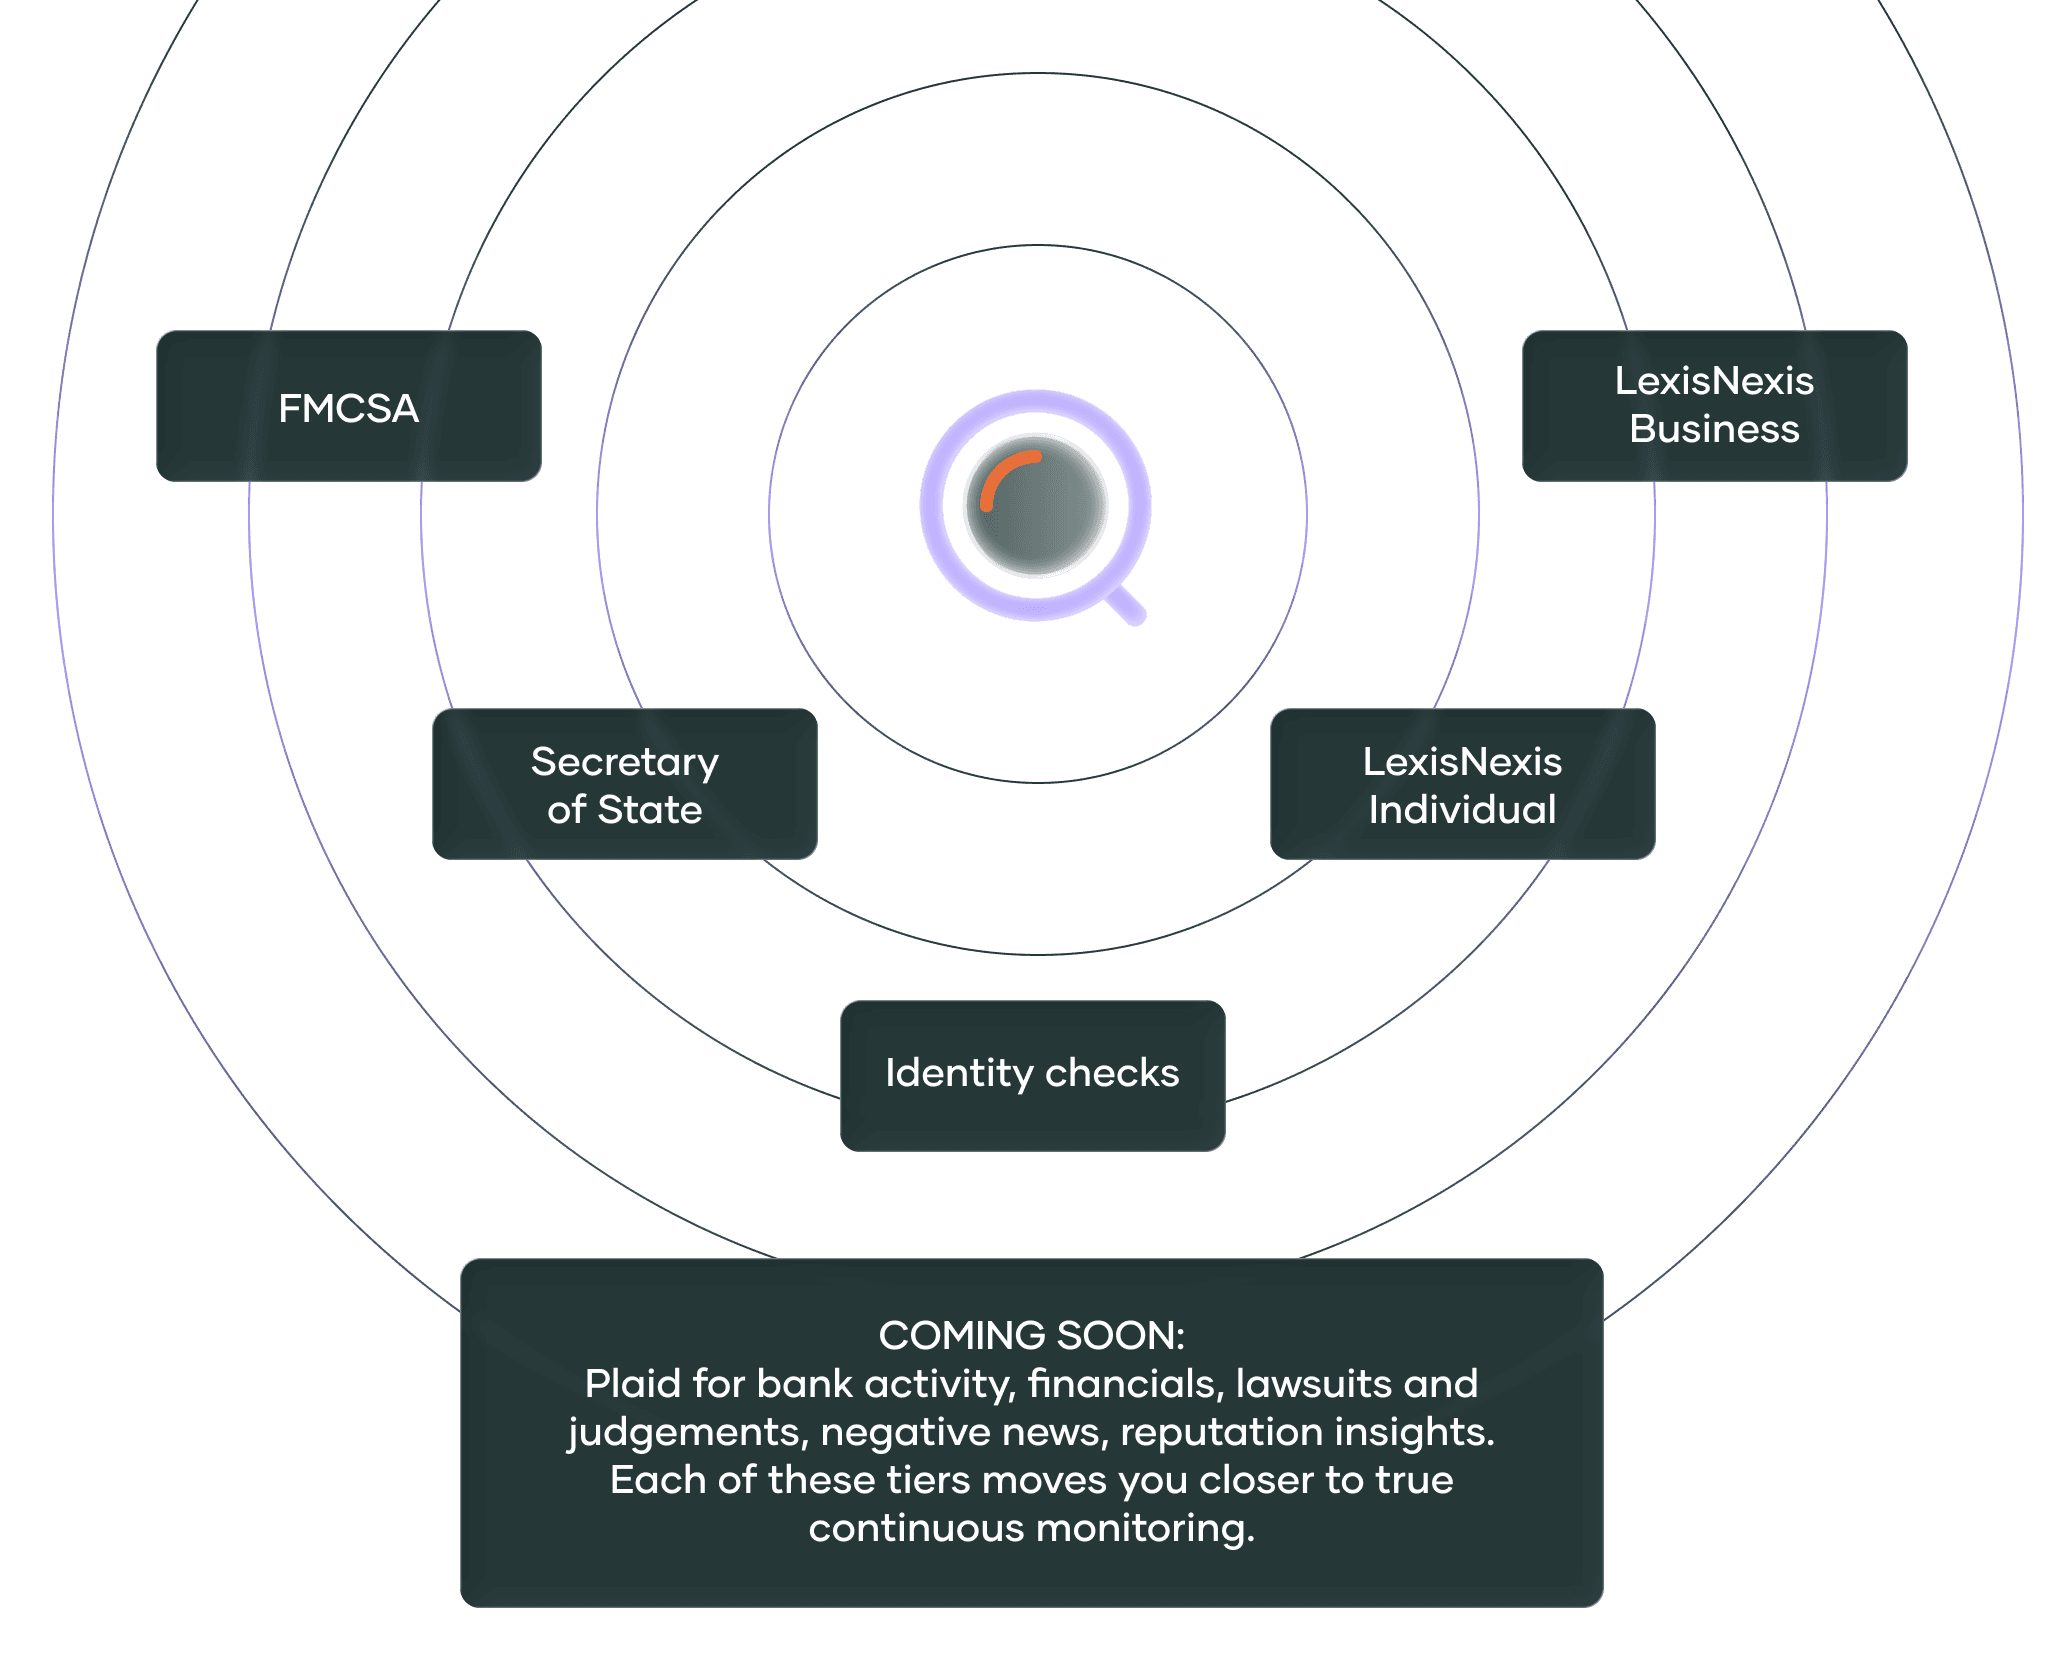
Choose what to monitor for each client, how often, and when. ROX pulls the data on your schedule, compares it to the last pull, and alerts you to any changes.
BENEFITS
This isn't just another feature. It's a fundamental shift from reactive to proactive portfolio management.
Catch warning signs before a good client becomes a bad debt. Stop preventable losses and protect your book.
Reach out with valuable insights when you see changes. Build better relationships and reduce risk through communication.
Monitor your entire book on a regular schedule without adding headcount. Free your team to focus on growth, not manual checks.
Schedule monitoring around compliance audits so your data is always current and defensible.
FLEXIBILITY
Not every client needs the same level of oversight. Match your monitoring cadence to your risk tiers.
Your monitoring. Your frequency. Your dashboard.
THE DIFFERENTIATOR
Nobody else in KYC/KYB and underwriting does this. Every competitor watches the front door. ROX watches the back door, too.
"Thank God for ROX. You saved me from onboarding a fraudulent client."
WHO THIS IS FOR
Monitor your entire book on schedule without adding headcount or manual work.
Get the earliest possible warning on deteriorating clients and intervene before it's too late.
Enable proactive outreach and better conversations when client data changes.
Easily pull monitoring reports and change logs to demonstrate compliance for a more efficient audit process.
WHAT TO LOOK FOR
Six questions to put to any tool, including ours.
Does it watch the signals that move your book: UCC filings and liens, credit events, Secretary of State status, and, for freight, FMCSA authority and insurance?
Can you set how often each client is re-checked, weekly for risky clients and annually for low-risk ones, instead of one schedule for the whole book?
Does it alert the people who can act, such as client services or risk, the moment something changes?
If you factor, does it watch the debtors behind the receivables as well as the client you onboarded?
Does it keep monitoring reports and change logs you can show an auditor?
Does it share a file with your underwriting and connect to your servicing platform, so a change lands next to the original decision?
ROX monitors FMCSA, Secretary of State, background, and UCC filings on a schedule you choose, alerts you to changes, and gives you monitoring reports and change logs for audits. For lien activity, UCC monitoring runs alongside UCC search and filing inside your underwriting flow.
FAQ
The best credit risk monitoring software for factors and lenders watches the signals that move your book (UCC filings and liens, credit events, Secretary of State status, and FMCSA data for freight), lets you set the cadence per client, alerts the right person, keeps change logs for audits, and connects to your underwriting and servicing platform. ROX monitors those signals on a schedule you choose for factors, lenders, and MCA funders, in the same file as the original underwriting decision, and connects to servicing platforms like FactorCloud.
A periodic review checks a client once a year, so a new lien, a lapsed registration, or a judgment can sit unnoticed until the next one. Continuous monitoring re-checks clients on a cadence you set and alerts you when something changes.
Read: real-time credit risk monitoring, from periodic audits to continuous detectionROX re-checks FMCSA, Secretary of State, background, and UCC filings, and alerts you to UCC changes, credit events, and lien activity. For factors it also watches AR aging and bank activity between fundings. For lenders it re-checks AR aging, financial trends, and public-record changes.
You set the cadence. Choose how often ROX re-checks each client: daily, weekly, monthly, or a schedule that matches your risk appetite. Monitor risky clients weekly or monthly, check low-risk clients annually, and set custom schedules for mid-tier clients. ROX pulls the data on your schedule, compares it to the last pull, and alerts you to any changes.
Watch how ROX monitors your entire portfolio and surfaces silent risk before a good client becomes bad debt.
Get Started Free